s Your Financial House in Order? 4 Year-End Financial Tips
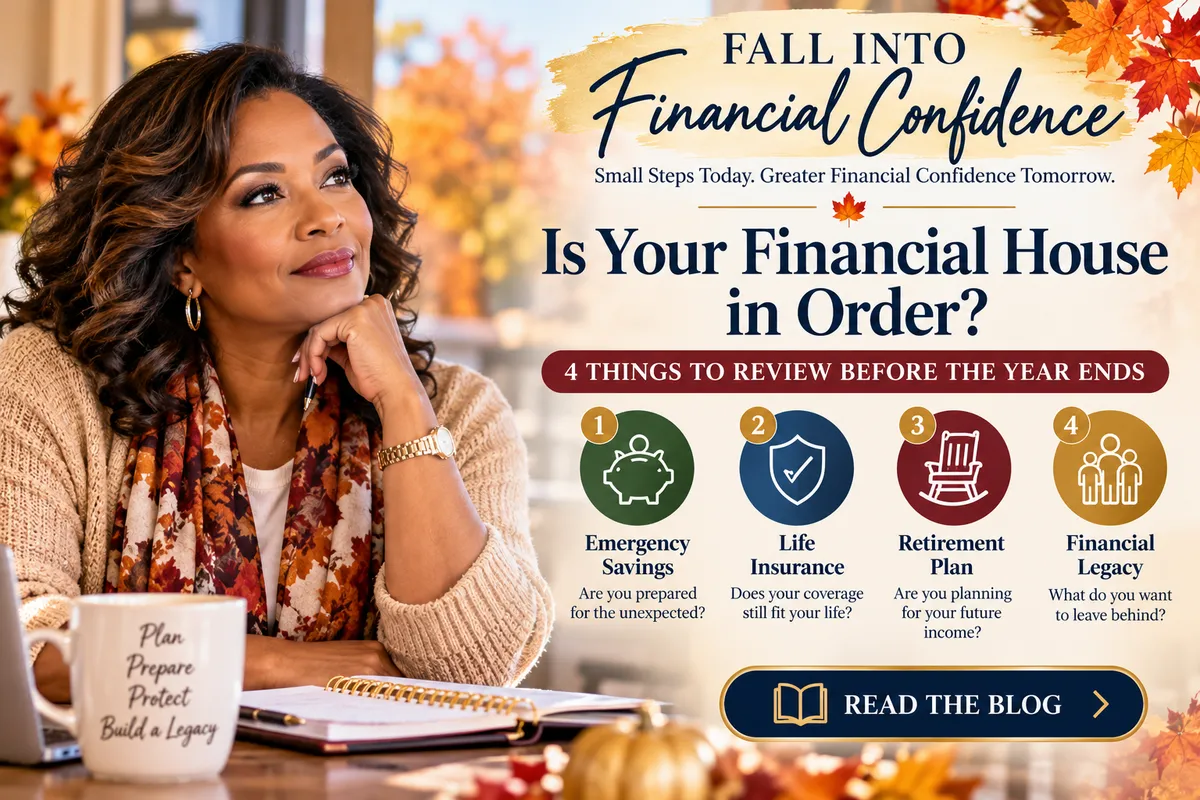
🍁 Is Your Financial House in Order? 4 Things to Review Before the Year Ends
Fall Into Financial Confidence: Small Steps Today. Greater Financial Confidence Tomorrow.
By Steven & Kimberly Simmons, Financial Professionals
As the leaves begin to change and the temperatures start to cool, many of us turn our attention to preparing our homes for the season ahead. We clean out closets, organize our spaces, tackle home maintenance projects, and make sure everything is ready for the coming months.
But here's a question worth considering:
When was the last time you gave your financial house that same level of attention?
Just like our homes, our financial lives need regular maintenance. Over time, our priorities change, expenses increase, families grow, and retirement gets a little closer.
The good news? You don't have to overhaul your entire financial life overnight. Sometimes, a few thoughtful adjustments can make a meaningful difference.
As we approach the end of the year, here are five important areas worth reviewing.
🍂 1. Your Emergency Savings: Are You Prepared for the Unexpected?
Life has a way of surprising us, and not every surprise is a pleasant one.
A major car repair, unexpected medical expense, home maintenance emergency, or temporary loss of income can quickly disrupt even a carefully planned household budget.
Having an emergency fund can help you manage these situations without immediately relying on credit cards or dipping into long-term retirement savings.
Financial professionals commonly suggest working toward three to six months of essential living expenses in an accessible emergency fund, although your individual needs may vary.
Financial Food for Thought:
If your household experienced an unexpected $5,000 expense tomorrow, would you be financially prepared?
If the answer is no, don't be discouraged. Building an emergency fund is a process, and even small, consistent contributions can help.
Your Fall Financial Action Step: Review your emergency savings and consider establishing an automatic monthly contribution if you haven't already.
🍁 2. Your Life Insurance: Does Your Coverage Still Fit Your Life?
Life insurance is one of those financial tools that many people purchase and then rarely revisit.
But think about how much life can change in just a few years.
Perhaps you've purchased a home, welcomed a new grandchild, started a business, increased your income, or begun thinking more seriously about retirement.
These changes can affect your financial responsibilities and the amount or type of life insurance coverage that may be appropriate.
Life insurance isn't simply about leaving money behind. Depending on the type of policy and its features, it may also play a role in broader financial planning strategies.
For example, certain permanent life insurance policies offer cash value features that may provide additional financial flexibility, although accessing those values can reduce policy benefits and may have tax consequences.
Financial Food for Thought:
If something happened to you tomorrow, would your current life insurance coverage provide the financial resources you want your loved ones to have?
Your Fall Financial Action Step: Review your current policies, coverage amounts, beneficiaries, and policy features. Make sure you understand what you own and whether it still aligns with your goals.
🍂 3. Your Retirement Plan: Are You Planning for Savings or Income?
Many people spend decades focused on one important retirement goal: saving as much money as possible.
And that's certainly an important part of preparing for retirement.
But there's another question that deserves just as much attention:
How will those savings translate into income when your regular paycheck stops?
Retirement planning involves more than accumulating money in a 401(k), 403(b), IRA, or other retirement account.
It also means considering how your various financial resources may work together to support your desired lifestyle.
Potential retirement income sources might include Social Security, pensions, personal savings, investments, and annuities.
Certain annuities can provide guaranteed income for a specified period or for life, depending on the contract and the financial strength of the issuing insurance company.
The right combination depends on your circumstances, goals, and tolerance for risk.
Financial Food for Thought:
Do you know approximately how much monthly income you'll need in retirement and where that income will come from?
Your Fall Financial Action Step: Estimate your anticipated retirement expenses and compare them with your expected income sources. Identify any potential gaps that deserve further attention.
🍂 4. Your Financial Legacy: What Do You Want to Leave Behind?
When people hear the phrase generational wealth, they sometimes imagine enormous fortunes, luxury estates, and millions of dollars passed from one generation to the next.
But creating a financial legacy doesn't have to mean leaving behind generational luxury.
Sometimes, generational wealth simply means leaving generational financial resources.
It might mean helping a grandchild attend college, providing financial stability for a surviving spouse, helping adult children purchase their first home, or ensuring loved ones aren't left struggling with unexpected expenses.
Your legacy may also include the financial lessons and values you pass along.
And remember, legacy planning isn't only for the wealthy. It's about making thoughtful decisions regarding the resources you've worked hard to build.
Financial Food for Thought:
If you could leave one meaningful financial gift or lesson to the next generation, what would it be?
Your Fall Financial Action Step: Review your beneficiaries, consider whether your estate planning documents need updating, and have a conversation with your family about your wishes. An estate planning attorney can help address legal documents and estate-specific concerns.
🍁 Your Financial House Doesn't Have to Be Perfect. It Just Needs Attention.
One of the biggest misconceptions about financial planning is that you need to have everything figured out before seeking guidance.
You don't.
Financial confidence doesn't necessarily come from having a certain amount of money in the bank. It often comes from understanding your financial situation, knowing your options, and taking intentional steps toward your goals.
Maybe your emergency savings need attention. Perhaps your life insurance hasn't been reviewed in years. Or maybe retirement is approaching, and you're beginning to wonder how your savings will translate into dependable income.
Whatever your situation, remember that progress begins with awareness.
Small steps today can help create greater financial confidence tomorrow.
🍂 Let's Fall Into Financial Confidence Together!
Throughout the remainder of October, we're focusing on practical financial education designed to help individuals and families make more informed decisions about their financial futures.
Our goal isn't to tell you what your financial future should look like. It's to help you understand the strategies and options available so you can make decisions that align with what matters most to you.
If you would like to review your current financial situation or simply learn more about your options, we invite you to schedule a complimentary financial education session.
No pressure. Just an opportunity to ask questions, gain clarity, and explore ideas for your financial future.
Steven & Kimberly Simmons
Financial Professionals
📞 (334) 801-2936
📧 [email protected]
🌐 www.sakfin.com
Fall Into Financial Confidence — Small Steps Today. Greater Financial Confidence Tomorrow.
Important Information: This article is intended for general financial education and does not constitute individualized investment, tax, or legal advice. Insurance and annuity products vary by contract, and guarantees are subject to the claims-paying ability of the issuing insurance company. Fixed indexed annuities do not directly participate in the stock market. Consult appropriately licensed professionals regarding your individual circumstances.
