How Much Life Insurance Do You Really Need?
How Much Life Insurance Do You Really Need?
When people think about life insurance, one of the first questions they often ask is:
“How much coverage do I actually need?”
You may have heard rules of thumb such as buying coverage equal to 10 times your annual income. While those guidelines can provide a starting point, determining the right amount of life insurance is usually much more personal.
The goal is not simply to choose a large number. The goal is to consider the financial responsibilities and people that could be affected if you were no longer here.
During Life Insurance Awareness Month, this is a great time to review your coverage and ask an important question:
Would the people I care about have enough financial protection if something happened to me?
Start With the People Who Depend on You
Life insurance is ultimately about protecting people.
Think about who currently depends on your income, financial support, or contributions to the household.
That may include:
A spouse or partner
Children
Aging parents
Family members with special needs
Business partners
Anyone who relies on you financially
Even if you are not currently the primary income earner, your contribution to the household still has value.
For example, replacing childcare, transportation, household management, caregiving, and other responsibilities could create significant expenses for a surviving family.
A Simple Way to Start: Think D.I.M.E.
One helpful starting point when estimating life insurance needs is to consider four important areas:
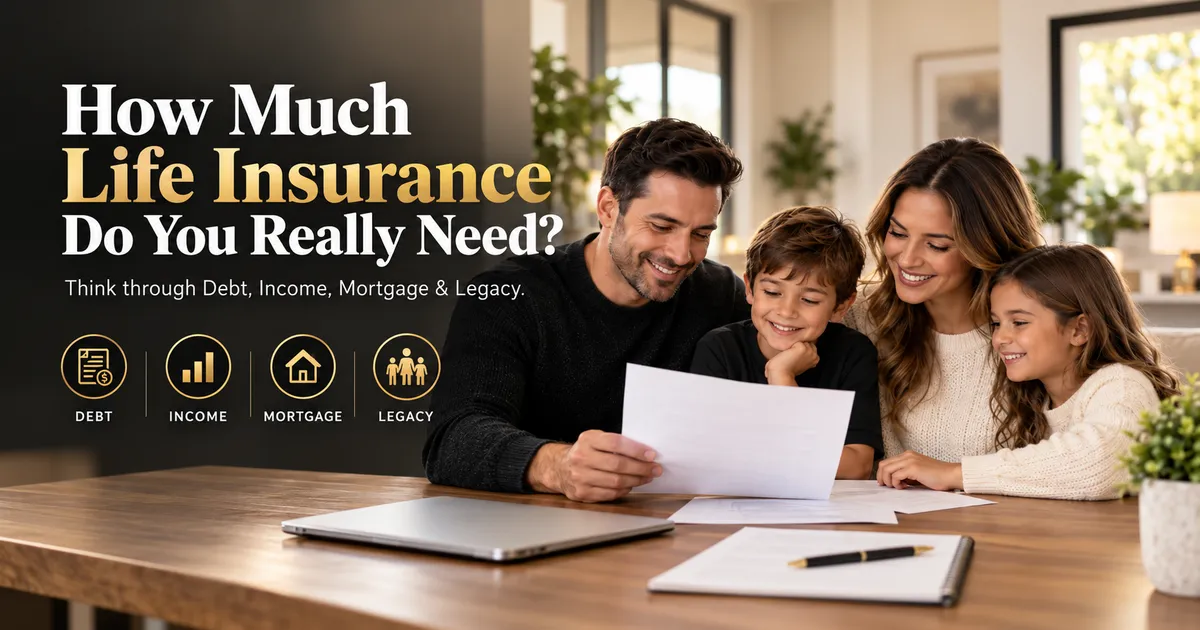
Debt
What debts would you want paid or reduced?
Consider things such as:
Credit cards
Auto loans
Personal loans
Student loans
Business-related obligations
The goal may be to prevent your loved ones from being left with financial obligations they may have difficulty managing on their own.
Income
How much income would your family need to replace?
If your household relies on your paycheck, consider how many years of income your family might need while adjusting financially.
For example, if someone earns $75,000 per year and wants to provide several years of income replacement, that amount alone could represent a significant portion of the life insurance need.
You may also want to consider future household expenses and inflation.
Mortgage
Would you want your family to remain in the home?
For many families, the mortgage is one of their largest monthly expenses.
Having enough life insurance to help pay off or significantly reduce the mortgage could provide your family with greater financial stability during an already difficult time.
Legacy
Finally, think beyond today's bills.
What would you like to leave behind?
Your goals might include:
Helping children attend college
Providing financial support for grandchildren
Leaving money to family members
Supporting a church, charity, or community organization
Creating an inheritance
Helping provide financial opportunities for future generations
Life insurance can be part of a broader legacy strategy designed to help transfer resources to the people and causes that matter to you.
Don't Forget Future Expenses
It is easy to focus only on today's bills, but your family's needs may continue for many years.
Consider expenses such as:
Education: If you have young children, how much might you want available for college, trade school, or other education?
Childcare: Would your surviving spouse need additional childcare or household assistance?
Final expenses: Funeral, burial, medical, and other final expenses can create an unexpected financial burden.
Care for family members: Do you financially assist an aging parent, adult child, or another family member?
These responsibilities should be considered when determining an appropriate amount of coverage.
Then Consider the Resources You Already Have
After estimating your family's financial needs, take a look at resources that may already be available.
These could include:
Existing life insurance
Employer-provided life insurance
Savings
Retirement accounts
Other financial assets
These resources may help reduce the amount of additional coverage needed.
However, employer-provided life insurance deserves special attention. Coverage offered through work can be a valuable employee benefit, but it may not always be enough to meet your family's needs, and in some cases it may not follow you if you leave the employer.
That is why it is important to understand both the amount of coverage you have and how that coverage works.
Life Changes — And Your Coverage Should Be Reviewed Too
The amount of life insurance that made sense five or ten years ago may no longer be appropriate today.
Consider reviewing your coverage after major life events such as:
Getting married
Having or adopting a child
Buying a home
Changing jobs
Receiving a significant raise
Starting or purchasing a business
Taking on significant debt
Becoming a caregiver
Approaching retirement
Experiencing a divorce
Becoming an empty nester
Even when there has not been a major life event, periodically reviewing your coverage can help make sure it still reflects your current responsibilities and goals.
So, How Much Do You Really Need?
There is no universal answer.
One family may need $250,000 of coverage while another may need $500,000, $1 million, or considerably more. Another household may discover that its needs have decreased as children become independent and debts are paid off.
The appropriate amount depends on your individual circumstances.
A better question than simply asking:
“How much life insurance should I buy?”
may be:
“If I were no longer here tomorrow, what financial responsibilities would I want taken care of for the people I love?”
That question can help bring the numbers into focus.
Protection Is About More Than a Number
Life insurance is not simply about leaving money behind.
It can help provide families with time, choices, stability, and peace of mind during one of the most difficult periods of their lives.
The right amount of protection can help a surviving spouse remain in the family home, allow children to continue pursuing their goals, provide time for a family to adjust financially, and help preserve the legacy someone worked years to create.
During Life Insurance Awareness Month, take a few minutes to review what you currently have.
Ask yourself:
Who depends on me?
What financial responsibilities would remain if I were gone?
Would my current coverage be enough?
Knowing your number is an important part of protecting the people and future that matter most.
Not Sure Where to Start?
At S&K Services, we believe financial education should come first.
We help individuals and families review their goals, understand their current protection, and explore options based on their individual needs and circumstances.
Learn more at sakfin.com.
Schedule a complimentary educational session: https://calendly.com/sksimmons-sakfin/30min
This information is provided for educational purposes only. Life insurance needs, products, features, costs, and availability vary based on individual circumstances and eligibility.
